Understanding Your Insurance Contract

Personne stressée en train d’examiner des documents à une table de cuisine, tandis qu’une autre se penche à côté d’un ordinateur portable

Before filling out your notice of loss, do you fully understand the subtleties of the coverages, clauses, and exclusions in your insurance contract?

Like most people, you may never have read your insurance contract in its entirety. You understand the broad strokes, of course, but in insurance, you often have to read between the lines.

We offer to review your insurance policy and your coverage with you in order to advise you on the best strategies to adopt for filling out your notice of loss and obtaining optimal compensation.

Our goal: to inform you about the world of insurance, the strategies to adopt, and the mistakes to avoid. The first meeting is free, confidential, and with no obligation on your part.

Building and Outbuildings Claim

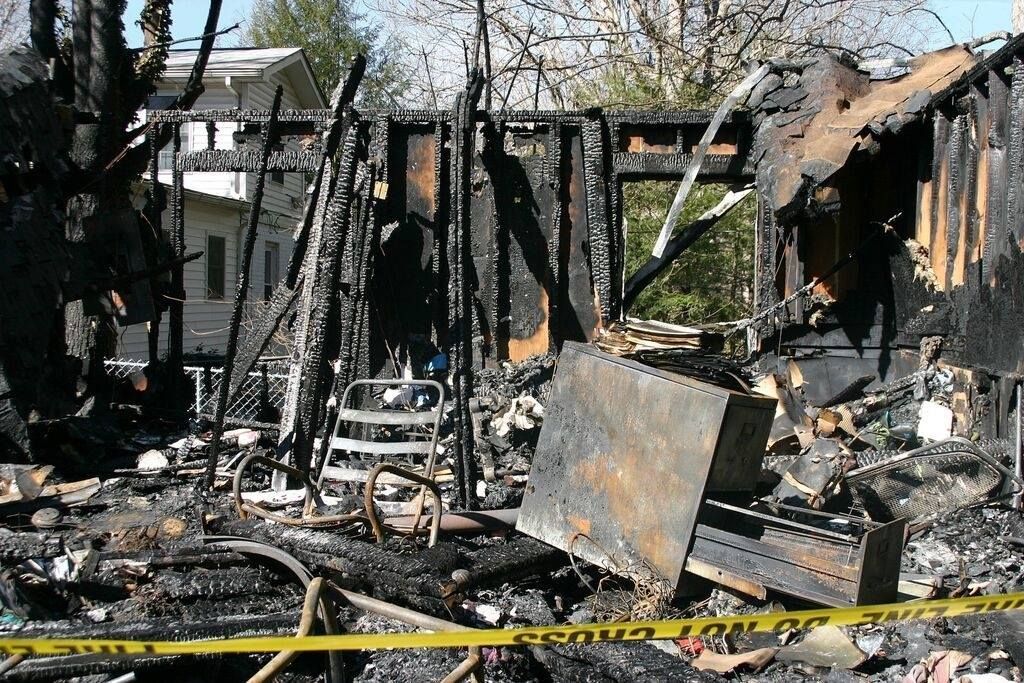
The building refers to any structure intended to shelter people, animals, or things. Outbuildings are the smaller buildings listed on your insurance contract, such as a detached garage or a shed. Your insurer's obligation is to put you back in a building that is in the same condition as before the loss.

You want your loss settled quickly.

We understand, but quickly proceeding with the demolition and reconstruction of your property is not recommended. The most logical approach is to take the necessary steps to reach a settlement agreement with your insurer before demolishing and rebuilding, so that all evidence of your loss is preserved until a settlement is obtained in your favour.

First, the value of your loss must be established, meaning the extent of the damage, the quality of the replacement materials, and the hours required for restoration by a skilled tradesperson. These precautions help avoid surprises, such as incurring costs higher than the amounts received, which would put you in a financial deficit.

You don't want to rebuild your home?

This is indeed an alternative solution. To do so, the applicable depreciation rates must be determined to establish the actual cash value of your building. These rates are calculated based on the wear of your home's materials and their normal lifespan. Some insurers include coverages in their contracts that allow you to obtain compensation without having to rebuild your home.

It is important to evaluate the options available to you in order to make an informed decision you won't regret.

Personal Property Claim

Personal property refers to the unattached items that were in your home. This includes all furniture, clothing, food, electronic devices, and much more. Your insurer's task is to replace or clean all the property that was damaged or lost during your loss.

You are required to prove your loss by producing an exhaustive list of your property or by verifying the lists provided by everyone involved in your file. This step is long and laborious; let our team help you.

In the event of partial damage to a set of personal property, your insurer is entitled to reimburse you for the replacement of only part of your set.

For example, if only two chairs from your kitchen set cannot be salvaged, the insurer could decide to compensate for those two chairs only, even if your kitchen set is no longer sold on the market. The insurer also reserves the right to pay the lesser of a repair or a replacement, for buildings as well as contents.

Have a question about your own contract?

Let's schedule a meeting.

More Posts

21 octobre 2026
Most of the time, to benefit from new replacement value, you must replace the property damaged in the loss.
21 octobre 2026
In recent years, we have observed in Quebec that natural disasters and other major losses seem to be becoming more and more frequent; it is not uncommon to see insurance companies overwhelmed by a high volume of claims.
21 octobre 2026
The insurance field is genuinely useful for policyholders' peace of mind, but it can prove complex. To come out well during a claim, you need to understand how it works.
21 octobre 2026
On top of being shaken by the events, you are the one who bears the burden of proving your loss. It is therefore in your interest to know the provisions of your insurance contract well in order to protect your rights throughout the process.
21 octobre 2026
The goal of anyone affected by a loss : to be back in the same situation as before the loss.
21 octobre 2026
Most of the time, to benefit from new replacement value, you must replace the property damaged in the loss.
21 octobre 2026
In recent years, we have observed in Quebec that natural disasters and other major losses seem to be becoming more and more frequent; it is not uncommon to see insurance companies overwhelmed by a high volume of claims.
21 octobre 2026
The insurance field is genuinely useful for policyholders' peace of mind, but it can prove complex. To come out well during a claim, you need to understand how it works.
21 octobre 2026
On top of being shaken by the events, you are the one who bears the burden of proving your loss. It is therefore in your interest to know the provisions of your insurance contract well in order to protect your rights throughout the process.
21 octobre 2026
The goal of anyone affected by a loss : to be back in the same situation as before the loss.